Health Insurance for Canadian Expats in France
AXA International, Bupa Global, Cigna Global, Allianz Care, and IMG Global are among the most trusted insurers for expats in France. These providers are well known for their comprehensive coverage and services designed specifically for those living abroad.
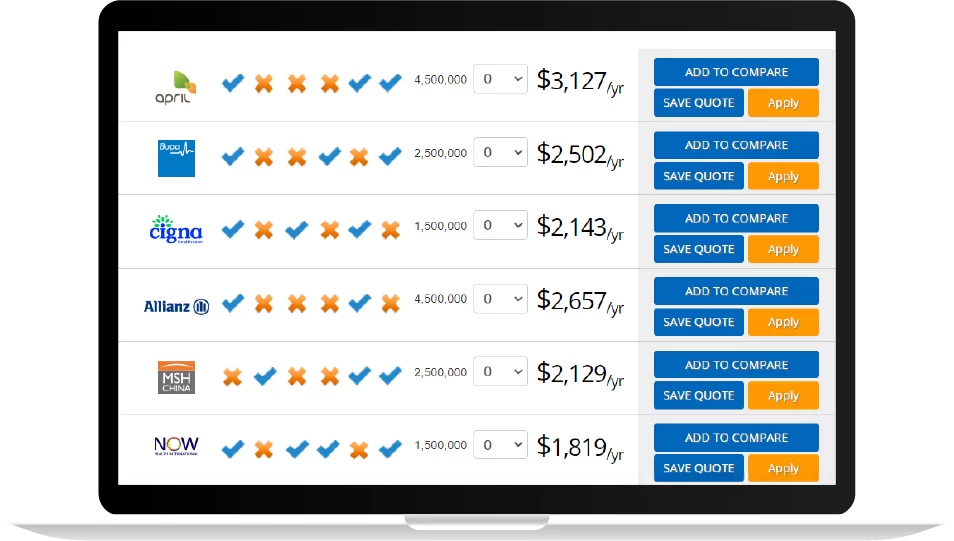
Discover the world's top
health insurers.
Compare quotes with
a click of the button.
Are you a Canadian planning a long-term move to France? If you’re curious about how France’s healthcare system works or want to find the right health insurance for your new life abroad, this article is for you.
In this Pacific Prime guide, we’ll explain how France’s healthcare system works, explore public and private health insurance options, compare costs across top providers, and help you find the best plans for Canadian expats living in France.
Understanding the French Healthcare System

Canada and France both offer strong public healthcare systems, but there are key differences to know before moving.
In France, all legal residents are covered under the universal public health insurance system called Protection Universelle Maladie (PUMa). This means that if you have a long-stay visa, work permit, or residency status, you’re generally eligible for the system.
Funding and Coverage of France’s Healthcare System
The French Social Security system funds its healthcare through contributions from employees, employers, and the self-employed. PUMa typically reimburses around 70% of costs for doctor visits, hospital stays, and prescription medications. Patients usually pay upfront and are reimbursed afterward.
To cover remaining costs and access additional services such as dental, optical, and specialist care, over 92% of the French population, including most expats, purchase supplementary private health insurance, also known as a mutuelle.
Key Differences from Canada’s Healthcare System
- Universal vs. Provincial Coverage: While Canada provides universal healthcare funded provincially, France’s PUMa is national and mandatory for all legal residents.
- Cost Control: The French government negotiates fees with providers and pharmacies, keeping costs lower than in many private healthcare systems.
- Reimbursement Model: Unlike Canada’s direct billing system, France requires upfront payment with reimbursement. A mutuelle plan helps cover most of the out-of-pocket costs.
International Recognition of France’s Healthcare System
France continues to earn global recognition for its healthcare system. In the 2024 World Index of Healthcare Innovation, France ranked 17th overall, up from 24th in 2022 and showing an 11-spot improvement since the index’s first report in 2020.
- Quality: Ranked 12th, with high marks for patient-centered care and disease prevention.
- Choice: Ranked 10th, thanks to low household catastrophic health spending and the freedom to select primary care providers and specialists. Some limitations remain in access to certain services and new treatments.
- Science & Technology: Ranked 14th, reflecting strong performance in scientific research and medical discoveries.
- Fiscal Sustainability: Ranked 30th, indicating some fiscal pressures in France’s largely government-funded healthcare system.
Legal Requirements for Health Coverage as a Canadian Expat
As a Canadian moving to France, it’s important to understand the mandatory health insurance rules to comply with visa and residency requirements. France has a universal healthcare system, meaning all legal residents, including expats, must have some sort of coverage.
Short-Stay Visa (Under 90 Days)
If your stay is less than 90 days (e.g., Schengen visa), you must have travel insurance that covers emergency medical treatment, hospitalization, and repatriation for the entire trip in France and the Schengen Area. The minimum coverage required is typically €30,000 (CAD $48,600).
Long-Stay Visa (Over 90 Days)
For stays over 90 days (work, study, or family visas), you’ll generally need to join the abovementioned France’s state health system known as Protection Universelle Maladie (PUMa).
- Initially, you must have private health insurance to cover the period from arrival until you are fully registered in PUMa, which usually takes around three months.
- After registering with the French social security system (CPAM – Caisse Primaire d’Assurance Maladie), you become eligible for PUMa, and enrollment is mandatory for all eligible residents.
Supplementary Private Insurance (Mutuelle)
PUMa typically reimburses about 70% of standard medical costs. Most expats also purchase a mutuelle to cover the remaining costs and access additional services such as dental, optical, and specialist care.
As a Canadian expat, it’s essential to make sure your health coverage meets French legal requirements to maintain residency status and avoid penalties. This also gives you access to comprehensive private healthcare beyond the French public system.
If you’re also curious about how living costs and healthcare expenses stack up in France, check out our detailed article on the cost of living in France, with breakdowns of housing, utilities, transport, and medical care.
Top Private Health Insurance Providers for Canadian Expats
At Pacific Prime, we partner with leading international insurers to offer customizable health insurance solutions for Canadians living in France. Some of the most trusted providers among expats include AXA International, Bupa Global, Allianz Care, Cigna Global, and IMG Global.
1. AXA International
AXA International is one of the most trusted names in global health insurance, known for its wide network, flexible coverage, and strong support for expats in France. AXA offers five tiers of international health insurance plans: Foundation, Standard, Comprehensive, Prestige, and Prestige Plus.
- Foundation Plan: Provides essential coverage with an annual limit of up to CAD $224,000. It includes inpatient hospital care, surgeries, emergency medical evacuation and repatriation, cancer treatment, ambulance transportation, and CT, PET, and MRI scans.
- Outpatient care, checkups, and vaccinations can be added as optional benefits.
- Standard Plan: Offers an annual limit of up to CAD $2,240,000. It includes all Foundation Plan benefits plus dental coverage for additional protection.
- Comprehensive Plan: Increases the annual limit to CAD $3,360,000, adding outpatient treatments, vaccinations, chronic condition coverage, and optical benefits such as eye exams and prescription glasses.
- Prestige Plan: Covers up to CAD $4,480,000 annually and builds on the Comprehensive Plan with maternity coverage and annual health checkups.
- Prestige Plus Plan: The most complete option, with a generous annual limit of CAD $11,200,000, covers all benefits from the Prestige Plan for maximum peace of mind.
AXA International also provides 24/7 personal assistance, virtual doctor consultations, and mental health support through its Mind Health Service. Claims are processed often within 48 hours, and policyholders can reduce premiums by excluding U.S. coverage if not needed.
2. Bupa Global
Bupa Global offers high-quality health insurance plans tailored for expats, families, and professionals. Known for its premium service and extensive global network, Bupa Global provides four main tiers of international health insurance: Major Medical, Select, Premier, and Elite.
- Major Medical Plan: The most essential plan, focused on emergency and major medical coverage. It includes medical evacuation and repatriation but excludes wellness and routine checkups. Annual limit: CAD $4,675,000
- Select Plan: Includes coverage for health screenings and wellness exams after a 10-month waiting period. Maternity, dental, and optical coverage are not included. Annual limit: CAD $2,337,500
- Premier Plan: Expands coverage to include vaccinations, dental and vision care, and wellness exams after a waiting period. This plan includes medical evacuation but not repatriation. Annual limit: CAD $3,506,250
- Elite Plan: The most comprehensive plan, offering medical evacuation and repatriation, routine maternity care, complementary therapies, and dental and optical coverage after a 10-month waiting period. Annual limit: CAD $7,012,500
All Bupa Global plans come with 24/7 multilingual support, a digital portal for claims management, and access to an extensive worldwide provider network. Members can also freely choose their doctor or hospital within their coverage region, ensuring peace of mind wherever they are in the world.
3. Allianz Care
Allianz Care is a globally recognized health insurance provider known for its extensive medical network, fast claims processing, and flexible plans designed for expats. Allianz offers three main international health insurance tiers:Allianz Care Base, Allianz Care Enhanced, and Allianz Care Pro.
- Allianz Care Base Plan: With a maximum plan limit of CAD $3,500,000, this plan provides comprehensive inpatient and day-care coverage, including semi-private hospital rooms, oncology treatments, emergency outpatient care, medical evacuation, rehabilitation, and home nursing.
- Allianz Care Enhanced Plan: Increases the annual limit to CAD $5,600,000. This plan includes all the benefits of the standard Allianz Care Plan, with an upgrade to private hospital rooms and emergency dental treatment coverage added for extra peace of mind.
- Allianz Care Signature Plan: The top-tier option, offering a maximum limit of CAD $7,000,000. It includes all the Plus Plan benefits, plus preventative surgery and laser eye treatment coverage for more comprehensive protection.
4. Cigna Global
Cigna Global is a leading international health insurance provider trusted by expats for its flexible global coverage and support network. Cigna offers three main plan tiers: Silver, Gold, and Platinum, each with worldwide coverage and an option to exclude the U.S. if you don’t need it.
- Cigna Silver Plan: The entry-level plan offers an annual limit of CAD $1,400,000. It provides full coverage for inpatient and day-patient care, private room accommodation, cancer treatment, and mental and behavioral health coverage up to CAD $7,000.
- Routine maternity care is not included under this plan.
- Cigna Gold Plan: With an annual limit of CAD $2,800,000, this plan expands benefits with higher limits for emergency care, advanced imaging (CT, MRI, and PET scans), rehabilitation, home nursing, and palliative care.
- Routine maternity care is included with coverage up to CAD $9,800.
- Cigna Platinum Plan: The most comprehensive tier, offering an unlimited annual limit. It includes all Gold Plan benefits plus hospital accommodation for a parent or guardian, transplant services, acupuncture and traditional Chinese medicine, and enhanced palliative care.
- Routine maternity coverage is also upgraded to CAD $19,600.
Cigna Global members enjoy 24/7 multilingual customer service, access to a worldwide direct billing network, and flexible options to tailor benefits, making it one of the most versatile choices for Canadian expats living in France.
5. IMG Global
IMG Global is a reputable international health insurance provider known for its flexible and comprehensive coverage tailored to expats and their families. For Canadian expats in France, IMG offers four plan tiers: Bronze, Silver, Gold, and Platinum.
IMG Global’s policyholders enjoy access to worldwide healthcare networks, emergency medical evacuation, and prescription drug coverage for peace of mind both in France and while traveling abroad.
- IMG Bronze Plan: The entry-level plan offers essential protection, including inpatient surgeries, outpatient care, physical therapy, prescription drugs, emergency ambulance services, and medical evacuation. This plan provides a lifetime limit of CAD 1,400,000 per individual.
- IMG Silver Plan: A step up from the Bronze plan, the Silver tier increases benefit limits across most categories, making it ideal for expats seeking broader protection without high premiums. It offers a lifetime limit of CAD 7,000,000 per individual.
- IMG Gold Plan: Designed for those wanting more comprehensive coverage, the Gold plan includes full inpatient and outpatient benefits, higher limits for medical services, and lifetime coverage for emergency evacuation. The plan offers a lifetime limit of CAD 7,000,000 per individual.
- IMG Platinum Plan: The most extensive option, offering premium protection with maternity and newborn care (after a 10-month waiting period), congenital condition coverage, and newborn wellness benefits unavailable in lower tiers. This plan provides a lifetime limit of CAD 11,200,000 per individual.
IMG Global also provides 24/7 international support, direct billing in hospitals worldwide, and the flexibility to customize your area of coverage, making it a top choice for Canadian expats looking for dependable international health insurance in France.
Protecting Your Health and Peace of Mind in France
For Canadian expats settling in France, having the right health insurance isn’t just about meeting legal requirements. It’s about you being able to fully enjoy life abroad with confidence.
By choosing a plan that suits your lifestyle and medical needs, you’ll gain comprehensive protection whether it’s for everyday doctor visits or emergency treatments. With that peace of mind, you can focus on what truly matters: embracing your new adventure in France.
With over 25 years of expertise, Pacific Prime helps Canadians find the best international health insurance for their time abroad. Whether you’re relocating for work, study, or retirement, our advisors can help you compare top insurers and select a plan that fits your budget and goals.
Get started today with a free, no-obligation quote from our insurance experts, and take the first step toward a healthier, worry-free life in France.
Frequently Asked Questions
Is healthcare free for expats in France?
Healthcare in France isn’t completely free for expats. The public system (PUMa) typically reimburses around 70% of most medical expenses. With private health insurance, expats can cover the remaining costs and gain easier access to private hospitals and English-speaking doctors.
What is the difference between public and private health insurance in France?
Public insurance (Assurance Maladie) covers essential care but often leaves gaps in dental, optical, and specialist services. Private health insurance fills these gaps, offering faster visits, better hospital choices, and full reimbursement for treatments not fully covered by the public system.
Can I use my Canadian health insurance in France?
Canadian health coverage doesn’t extend overseas. Expats in France need local or international private health insurance to meet visa requirements and ensure full protection. A private plan ensures you’re covered for both public and private care while living abroad.
With his keen interest in journalism, especially in the healthcare and wellness field, Tawan joins Pacific Prime with the goal of creating content that simplifies health insurance solutions, helping people make informed choices and choose the best options for their needs.
- Cigna Global Health Insurance in Thailand for Expats - August 5, 2026
- UAE Family Health Insurance: Coverage for 2026 - May 28, 2026
- Opening a Bank Account in Mexico: 2026 Guide for Expats - April 7, 2026
Comments
Comments are disabled for this post