
Health Insurance for British Expats in Germany 2026 Guide
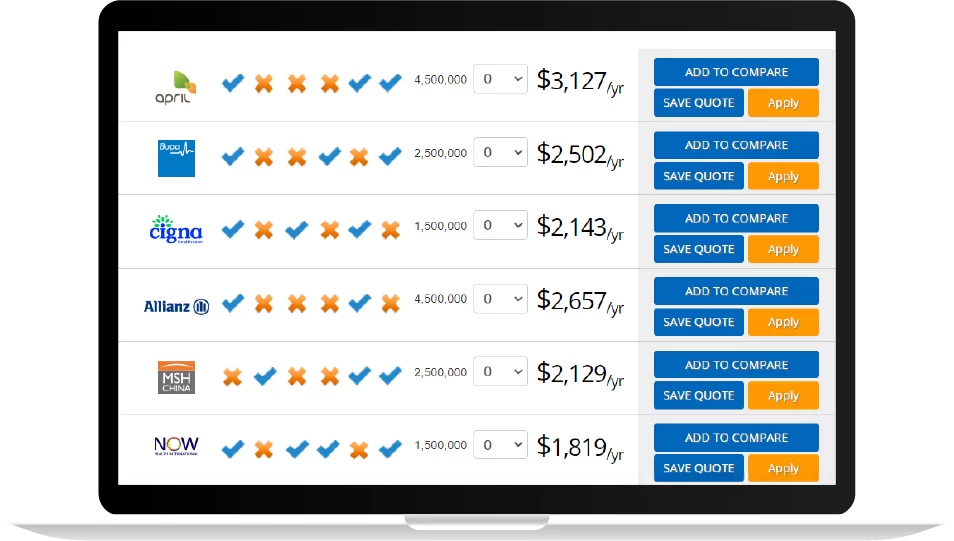
Health insurance in Germany is mandatory for all residents, including British expats. Foreigners can choose between the statutory scheme and a privately paid plan. The best private health insurance providers are AXA, Allianz, April International, Bupa, and Cigna.
Discover the world's top
health insurers.
Compare quotes with
a click of the button.
Are you a British expat moving to Germany soon? Need help finding the right health insurance for your needs?
This article will detail how Germany’s healthcare system is organized, how British expats can access care, who the best providers are, and how much expats should expect to pay monthly on premiums, plus more!
We also recommend checking out the top international health insurance companies in Germany for expats to find the best plan available.
Overview of Germany’s Healthcare System: For Expats
Germany offers one of the most comprehensive and structured healthcare systems in Europe, supported by mandatory insurance and broad benefit coverage. As a British expat, you should focus on ensuring timely registration and understanding which insurance route (SHI or PHI) applies to you.
As a British expat, you will need to register for health insurance once you become a resident in Germany to ensure legal compliance and access to care. There are two types of insurance expats can use in Germany:
- Statutory Health Insurance (SHI): The majority of residents (around 89%) are insured via non-profit “sickness funds”.
- Private Health Insurance (PHI): Higher earners, self-employed individuals, or civil servants may choose or be eligible for private insurance instead of SHI.
- Benefit Coverage: The SHI system provides broad benefits, including outpatient, inpatient, maternity, rehabilitation, and prescription drugs.
- Contributions: Funding is shared between employer and employee for SHI, based on income; PHI premiums are risk-based.
- Provider Access & Quality: Germany is recognised for its strong infrastructure, high standard of care, and effective access to specialist services.
Your residence status in Germany triggers the requirement to join a health insurance scheme, so it matters early in your move.
Depending on your employment status, income level, and whether you’re self-employed, you may be placed into SHI or eligible for PHI; knowing the difference matters for cost and benefits.
How Britain’s Healthcare System Compares to Germany’s
The British National Health Service (NHS) and Germany’s dual public–private healthcare system share the goal of universal coverage but differ sharply in funding, structure, and patient experience. Understanding these contrasts helps British expats adjust expectations when relocating.
Core System Differences
- Funding Models: The NHS is financed primarily through general taxation, while Germany’s system is funded by mandatory income-based insurance contributions shared between employers and employees.
- Insurance Structure: Britain operates a single-payer model under the NHS. Germany has a dual system—Statutory Health Insurance (SHI) for about 89% of residents and Private Health Insurance (PHI) for higher-income earners and self-employed individuals.
- Choice and Competition: NHS patients generally register with one GP in their area, while Germans can choose among over 100 non-profit sickness funds and have direct access to most specialists without a referral.
- Wait Times and Accessibility: Germany’s decentralized system results in significantly shorter wait times for consultations and elective procedures compared with the NHS.
Quality and Patient Experience
- Care Quality: Both systems maintain high standards, but Germany often ranks higher for hospital infrastructure, technology use, and patient satisfaction.
- Prescription Access: In Germany, patients pay small co-payments for prescriptions, while the NHS offers capped fees or free medication for certain groups.
- Language and Communication: Many German doctors speak English, but the system’s documentation, billing, and communication styles may be more bureaucratic and formal than those in the UK.
Financial Implications for British Expats
- Cost Perception: British expats accustomed to free-at-point-of-use care may find German healthcare more expensive, though insurance contributions ensure broad, predictable coverage.
- Employer Contributions: If you work in Germany, your employer automatically contributes to your SHI, reducing out-of-pocket expenses.
- Private Plan Benefits: High-income earners opting for PHI can access additional perks, such as private hospital rooms and shorter wait times, though premiums increase with age and medical history.
Can British Expats Use Public Healthcare in Germany?
British expats can use Germany’s public healthcare system through Statutory Health Insurance (SHI) if they live and work in the country. Enrollment in an approved public insurer, called a Krankenkasse, grants access to Germany’s extensive network of doctors, hospitals, and pharmacies.
Here’s a summary of the eligibility and coverage for British expats:
- Employed British expats earning below about EUR 73,800 annually in 2026 are automatically placed in SHI, with contributions split between employer and employee.
- Self-employed individuals and students can also join voluntarily, while dependents are typically included under a family policy at no extra charge.
Public insurance covers doctor visits, hospital care, maternity, dental, and preventive checkups, with only small co-payments for prescriptions. However, high earners and non-working residents must choose between public and private insurance, as switching back to SHI later can be difficult.
Private Health Insurance for British Expats in Germany
Private health insurance (PHI) in Germany offers more flexibility and personalized care options for British expats, especially those who are self-employed, high-income earners, or ineligible for the public system. It’s also a common requirement for long-term visa and residence permit applications.
Private health insurance is essential for many British expats, either for visa compliance or enhanced comfort and choice. Comparing both local and international providers ensures the best balance between flexibility, cost, and comprehensive coverage.
Why British Expats Choose Private Insurance
Many British expats opt for PHI to access shorter wait times, English-speaking specialists, and private hospital rooms. Private plans also offer customizable benefits for maternity, dental, and global travel. These advantages are not always available through SHI.
Those earning above the income threshold or coming on self-employment or freelancer visas often rely on PHI to meet visa and residency criteria.
Local vs. International Providers
Local German insurers such as Debeka, Allianz, and DKV specialize in domestic plans tailored to residents. These are ideal for long-term stays but may have limited overseas coverage.
In contrast, international providers like Bupa Global, AXA, and Cigna Global offer cross-border protection, perfect for British expats who travel frequently or plan to return to the UK in the future.
Average Cost of Medical Insurance in Germany
For British expats, monthly premiums typically range from €350 to €800, depending on income, age, and level of coverage. The average cost of health insurance in Germany depends on whether you’re enrolled in Statutory Health Insurance (SHI) or Private Health Insurance (PHI).
Here are some typical monthly premiums for insurance in Germany:
| Insurance Type | Average Monthly Cost (€) | What It Includes |
| Statutory Health Insurance (SHI) | €350 – €500 | Income-based contributions cover most medical, hospital, and preventive services. |
| Private Health Insurance (PHI) | €400 – €800 | Custom coverage for higher-income earners, including private rooms, English-speaking doctors, and global protection. |
| Student Health Insurance | €110 – €130 | Reduced public rate for international students under 30 years old. |
| Short-Term Expat Plans | €120 – €250 | Temporary coverage for newcomers or freelancers awaiting residence approval. |
Key Cost Factors
- Income Level: SHI contributions are a fixed percentage of gross salary, while PHI premiums are based on personal health and age.
- Family Status: Public plans include dependents for free, while private policies charge per person.
- Provider Choice: International insurers typically cost more but offer English support and worldwide coverage.
British expats can expect to spend between €350 and €600 per month for quality health insurance in Germany. Public insurance is best for employed expats, while private or international plans suit freelancers, higher earners, and frequent travelers.
Recommended Insurance Providers in Germany for Expats
AXA Global, Allianz Care, April International, Bupa, and Cigna Global are our top recommended insurance providers for British expats living in Germany. Each of these are reputable international health insurance provider offering global coverage, customizable benefits, and English-language support.
Below are six of the most trusted insurers, all of which have strong reputations for serving expatriates across Europe and beyond. You can compare quotes from these and other top insurers with our insurance quote generator.
AXA Global in Germany
AXA Global is one of the world’s largest and most established insurance groups, headquartered in France with operations in over 50 countries, including a strong presence in Germany. The company serves more than 105 million clients globally, providing a range of health, life, and travel insurance.
AXA is ideal for British expats in Germany seeking reliable international coverage with flexible options for both private and corporate plans. Their German branch offers efficient customer service in English, digital claim management, and strong hospital networks across Europe.
Expats appreciate AXA’s financial stability, prompt reimbursements, and broad global reach.
Core Plans for Expats:
- AXA Global Health Plan
- AXA International Exclusive
- AXA Foundations Health Plan
Allianz Care in Germany
Allianz Care, founded in Munich in 1890, is one of Germany’s most respected and internationally recognized insurers. It serves over 120 million customers worldwide and offers some of the most comprehensive expatriate medical insurance plans on the market.
For British expats, Allianz provides seamless access to healthcare both in Germany and abroad. Its global expat plans include international hospital coverage, medical evacuation, preventive care, and mental health services.
The company’s German roots ensure expats enjoy excellent local support and access to premium clinics within its extensive national network.
Core Plans for Expats:
- Allianz Care Core
- Allianz Care Classic
- Allianz Care Premium
April International in Germany
April International is a France-based global insurer that specializes in health coverage for expatriates. Operating in over 180 countries, it has built a reputation for simplicity, flexibility, and multilingual service, making it especially appealing for Britons adjusting to life in Germany.
April’s expat health plans are known for their customizable benefits and modern digital management tools. Policyholders can manage reimbursements through a mobile app, access telemedicine, and receive assistance in English and French.
The insurer also offers coverage that extends outside the EU, which is useful for British citizens traveling between Europe and North America.
Core Plans for Expats:
- April MyHealth Essential
- April MyHealth Comfort
- April MyHealth Elite
Bupa Global in Germany
Bupa Global, headquartered in the UK, is a leader in international private medical insurance with over 38 million customers in 190 countries. Known for its premium-level service and extensive global hospital network, Bupa offers expats a luxurious healthcare experience with top-level customer care.
For Britons in Germany, Bupa stands out for its world-class hospital partnerships and strong emphasis on preventive and mental health services. Expats benefit from 24/7 multilingual assistance, quick reimbursements, and the ability to receive treatment anywhere in the world.
This includes temporary visits back to Britain.
Core Plans for Expats:
- Bupa Global Select
- Bupa Global Premier
- Bupa Global Elite
Cigna Global in Germany
Cigna Global is a U.S.-based health insurance leader with over 180 million customer relationships across more than 200 markets. The insurer is widely regarded among expats for its flexibility, global support infrastructure, and easy online policy management.
British expats in Germany appreciate Cigna’s customizable global health plans, which allow them to add modules like dental, vision, outpatient care, or maternity benefits.
Cigna’s strong international provider network and dedicated expat assistance make it one of the most convenient and reliable insurers for those frequently traveling between Europe and North America.
Core Plans for Expats:
- Cigna Global Silver
- Cigna Global Gold
- Cigna Global Platinum
Special Considerations for British Expats
British expats must navigate visa rules, mandatory insurance laws, and procedural differences when settling in Germany. Proper documentation and a clear understanding of SHI versus PHI are essential for a smooth transition and uninterrupted healthcare coverage.
You should become aware of post-Brexit changes and differences between the two countries’ systems. Understanding these nuances helps ensure continuous coverage, visa compliance, and seamless access to care.
Key Things to Know:
- Post-Brexit Coverage Changes: The European Health Insurance Card (EHIC) from the UK is no longer valid for long-term stays in Germany. British citizens must secure full public or private health insurance to meet residence and visa requirements.
- Residency and Visa Requirements: Proof of health insurance is mandatory when applying for residence permits. Whether employed or self-employed, British expats must show evidence of SHI or PHI coverage before approval.
- Transfer of Medical History: Bring copies of medical records, vaccination history, and prescriptions in English or German to ensure continuity of care when registering with a German doctor.
- Cultural and System Differences: Germans typically book appointments directly with specialists, unlike the GP referral model in the UK. Expect more structured billing and reimbursement systems.
- Tax and Reimbursement Implications: Premiums for private health insurance may be tax-deductible in Germany, but British expats should seek advice on cross-border tax implications if they maintain financial ties to the UK.
How Expats Apply for Health Insurance in Germany
Applying for health insurance in Germany as a British expat involves several clear steps, including determining your eligibility, collecting the required documents, and applying for the plan of your choosing.
Following the correct order ensures your coverage is valid for both healthcare access and visa compliance.
Step-by-Step Process
- Determine Eligibility for Public or Private Insurance:
First, assess whether you qualify for Germany’s Statutory Health Insurance (SHI) or Private Health Insurance (PHI). Employees earning under €73,800 per year (as of 2026) are required to join SHI, while higher earners can opt for PHI.
- Collect Required Documents:
Prepare essential documents, including your passport, residence permit (if available), proof of income or employment contract, address registration (Anmeldung), and previous health coverage details from the UK.
- Register with a Health Insurance Provider:
Choose a public insurer like TK, AOK, or Barmer, or a private one such as Allianz or AXA. Once selected, complete their registration forms and submit your documents online or in person.
- Receive Insurance Confirmation Certificate:
After processing, you’ll receive a Versicherungsbestätigung (insurance certificate). This document is required for your residence permit application and to activate healthcare access.
- Register with a Doctor and Begin Coverage:
Once insured, choose a general practitioner (Hausarzt) for primary care. Present your insurance card (Gesundheitskarte) at each visit to receive treatment covered under your plan.
Tips for Foreigners to Save on Premiums in Germany
British expats can reduce health insurance costs in Germany by making strategic choices and understanding how public and private plans are structured. Here are the top five tips to save without sacrificing coverage.
- Choose the Right Deductible
Selecting a higher annual deductible lowers monthly premiums for private plans. For many expats, a deductible of €500–€2,000 balances affordability with protection.
- Compare Local vs. International Providers
Local German insurers (e.g., TK, AOK, Barmer) may offer lower premiums than international plans. International providers add global coverage but cost more, so choose based on travel habits and healthcare needs.
- Opt for Annual Payments
Paying premiums annually instead of monthly often results in a 5–10% discount, saving hundreds of euros over the year.
- Review Coverage Regularly
Reassessing your plan each year allows you to remove unnecessary benefits or adjust limits, keeping costs in line with your current lifestyle.
- Leverage Employer Contributions
If employed, your employer automatically contributes to your SHI or may subsidize PHI premiums. Factor this into your budget to minimize personal payments.
Frequently Asked Questions
What insurance do I need as a British expat in Germany for my visa?
British expats relocating to Germany must obtain comprehensive health insurance—either public (SHI) or private (PHI)—before converting their visa to a residence permit, as proof of coverage is mandatory for registration.
Can I keep my UK NHS coverage in Germany?
UK NHS benefits do not apply long‑term in Germany; once you register as a resident, you must enroll in Germany’s health insurance system (SHI or PHI), and your UK EHIC alone will not suffice for full coverage.
Is private health insurance better for British expats in Germany?
Private insurance offers perks like private rooms or English‑language services, but whether it is better depends on your income, family status, and long‑term plans. For many British expats, the public system may be more suitable.
How much does health insurance cost for expats in Germany?
Public SHI contributions in Germany are income-based, typically 14–15% of an expat’s gross salary, while private plans range widely from €300 to €800 per month, depending on age, coverage, and health. Health insurance costs vary depending on whether you join SHI or PHI.
Can my family be covered under my German health insurance plan?
Dependents in Germany without income are generally included at no extra cost under public health insurance. Private plans usually charge per person, so expats must consider family premiums when selecting PHI for comprehensive coverage.
Conclusion: More Expat Resources
British expats in Germany can access high-quality healthcare by understanding the public and private insurance systems, meeting residency requirements, and selecting plans that suit their lifestyle and travel habits.
Early registration ensures uninterrupted coverage and compliance with German law. To discuss your questions with an international health insurance expert, contact our team online or via a call to +852-3113-1331.
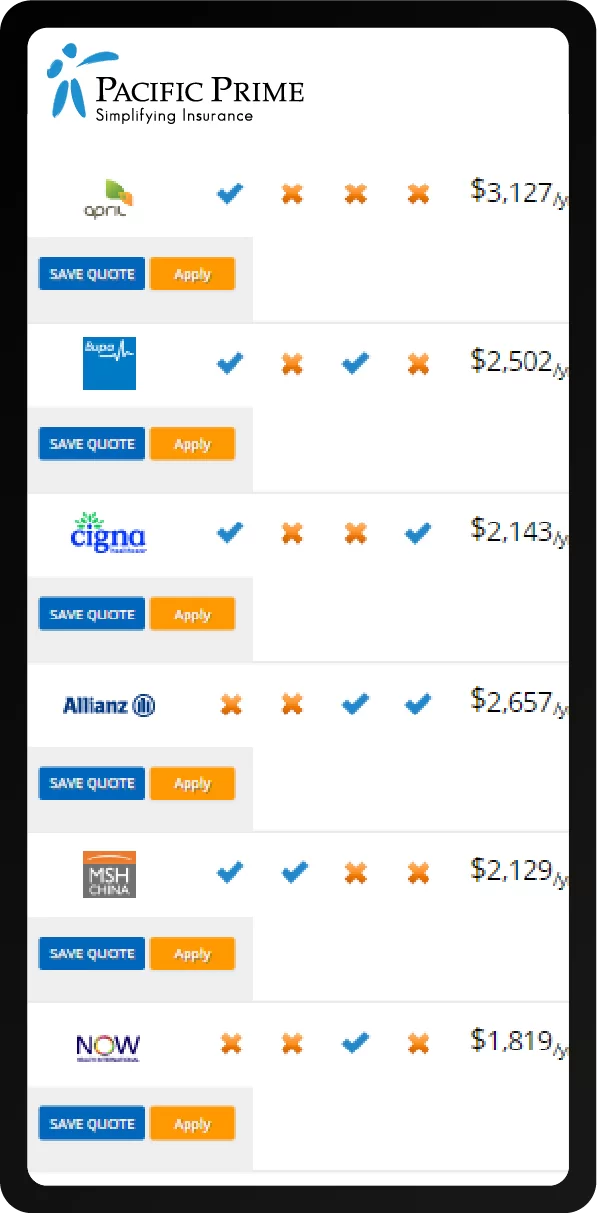
You can begin comparing quotes and plans from the top providers right away with our insurance quote generator that has over 50,000 plans in its database.
We recommend British expats explore the following resources before their move:
- Health Insurance for British Expats in France
- Health Insurance for British Expats in Italy
- Health Insurance in Germany for Expats: Public vs Private Plans
- Guide For Living Abroad In Germany
- Britain’s Travel Advisory for Germany
- Germany’s Ministry of Health
Serena earned her Bachelor’s Degree in Psychology from the University of British Columbia, Canada. As such, she is an avid advocate of mental health and is fascinated by all things psychology (especially if it’s cognitive psychology!).
Her previous work experience includes teaching toddlers to read, writing for a travel/wellness online magazine, and then a business news blog. These combined experiences give her the skills and insights she needs to explain complex ideas in a succinct way. Being the daughter of an immigrant and a traveler herself, she is passionate about educating expats and digital nomads on travel and international health insurance.
- An Expat’s Guide To East Coast Singapore - November 3, 2026
- Hospitals in New Zealand for Expats & Visitors (2026 Guide) - October 16, 2026
- Top 9 Health Insurance Companies for Expats in Malta - October 7, 2026
Comments
Comments are disabled for this post