
International Medical Insurance Guide 2026 for Expats
International medical insurance provides healthcare coverage for expats living abroad. These plans are globally portable, offering comprehensive treatment worldwide. Most are customizable to your health needs and budget, with benefits tailored to the lifestyles of expats and frequent travelers.
Discover the world's top
health insurers.
Compare quotes with
a click of the button.
Are you an expat preparing to move abroad? Are you wondering about the best way to ensure you have medical coverage that fits your needs worldwide?
In this Pacific Prime article, we will guide expats working abroad on how international health insurance works, how they can find a policy that’s right for them, and how to find the right insurance provider. We’ll also give tips for getting and using health insurance abroad.
How International Medical Insurance Works
International medical insurance provides healthcare coverage for a person residing internationally. This type of insurance plan is designed to provide global coverage to alleviate medical expenses while overseas.
If you are planning to work abroad, international health insurance is important to secure your medical coverage. While you may be able to access public healthcare, some countries do not allow expats to use public healthcare services.
It’s important to look into reputable international health insurance providers to have the best coverage and benefits for your needs.
Explaining the Different Types Of Insurance For Expats Abroad
Short-term medical insurance covers you when traveling abroad on work trips, while long-term plans are for when you’ll be living and working outside your home country. International health insurance plans offer global and regional coverage based on your needs.
Here are the types of insurance to consider when working abroad:
- Single-trip travel insurance with international medical coverage is ideal for a business trip or vacation up to approximately 30 days.
- Multi-trip travel insurance with international medical coverage covers multiple short trips abroad over the course of a year.
- International medical insurance is for expats who reside outside of their home country for most of the year. Policies are for at least a year and can be renewed. Many insurance companies offer lifetime renewal options.
There are also special insurance coverage considerations. If you are planning to start or grow your family abroad or if you have pre-existing conditions, you will need to learn more about coverage for those situations.
- Maternity insurance has a waiting period before coverage begins, so expats working abroad need to plan ahead when selecting coverage.
- Pre-existing condition coverage is difficult to obtain. The best chance is to get a policy through your employer or a group, but there may be individual options depending on your condition(s) and the insurance company.
What Happens if You Get Sick or Injured While Working Abroad
If you get sick or injured while working abroad, international medical insurance coverage will pay for the medical expenses according to your policy terms and limits. Contact your insurance provider for assistance in locating an in-network provider.
Some policies provide direct billing arrangements where the medical provider files a claim directly with the insurance provider. Some policies reimburse the insured after filing a claim.
International health and travel insurance companies network with medical providers abroad and offer assistance to locate providers who speak the same language.
Refer to your policy terms or contact the insurance company for assistance if you have any questions about whether or not your policy covers your condition. Be aware that intentional harm or injuries from the policyholder’s criminal activity are usually not covered.
Preventative Care and Wellness While Working Abroad
Some insurance plans offer preventative, routine, and wellness care coverage on plans for expats working abroad. While this coverage may have a higher premium, you will have higher benefit limits and fewer out-of-pocket medical costs.
If you have your family with you overseas, you can also have your children or partner covered in an international health insurance plan. Some plans may cover children under a certain age at no additional cost, subject to underwriting.
While you may be far away from your home country, having an international health insurance plan can give you peace of mind while working abroad. Your health is always a priority, no matter where you are.
When working abroad, make sure you communicate effectively with your health insurance provider. Always call your insurance company before getting medical care if feasible. When that’s not possible, contact the insurance company right away. Communicate in writing when the situation may be complex.
Follow these tips for phone calls with your medical insurance company:
- Write down the name of the insurer’s representative you are speaking with so you can follow up with the same person.
- Ask about their direct extension to simplify contacting them with follow-up information or questions.
Follow these tips for written communication with your medical insurance company:
- Make sure correspondence with your insurance company has accurate information, including dates, medical facilities, provider names, and medical information.
- Providing specifics can be helpful, but make sure your personal information is kept secure by only using secure channels to communicate.
Communication in writing is the clearest and best way to communicate with your insurance company. It makes keeping track of information and avoiding misunderstandings easier. The more complicated your situation is, the more advantageous written communication becomes.
Once you’ve secured an insurance plan, it’s important to remember that you can keep in touch with your insurance company for assistance or issues. Whether you need help with locating an in-network healthcare provider or you’re filing a claim, don’t hesitate to reach out to them when you need help.
Need Help With Provider Networks and Direct Billing
Most large international health insurance providers offer extensive direct billing networks so that the hospital or clinic can send medical bills directly to your insurance company. Using in-network providers helps keep your out-of-pocket medical expenses lower while working abroad.
To utilize direct billing networks, keep your insurance card and policy information with you. This will make it easier for your medical provider to contact the insurance company on your behalf when needed.
Also, call or check your insurance provider’s website to verify that a provider is in-network and the services are covered.
Clarify Pre-Approval or Pre-Certification Requirements
Many private health insurance plans require pre-approval (also called pre-certification) before major medical care like surgery, procedures, or treatments. Contact your insurance company before receiving care whenever possible to verify whether or not you need preapproval for the care to be covered.
Keeping Track of Records, Bills, and Documents
Keep track of your medical records, bills, and policy documents. Medical records help providers offer the proper care, and they can be used to advocate for treatments to be covered by insurance. Bills and policy documents can help in the event of billing mistakes or clearing up confusion.
Filing a Medical Claim With Your International Insurance Company
Filing a claim with your international health insurance company is easier than ever because most companies allow you to file requests online or in their app. Ensure the accuracy of all information in the claims, as incorrect details may lead to denial.
If the medical provider is filing the claim on your behalf, make sure names, spellings, and medical insurance policy information are correct.
Pacific Prime offers a dedicated claims-filing team to assist clients with filing claims with their chosen insurance provider. Purchase your international health insurance policy with Pacific Prime to receive these value-added services at no additional cost to you.
Finding the Right International Health Insurance Provider
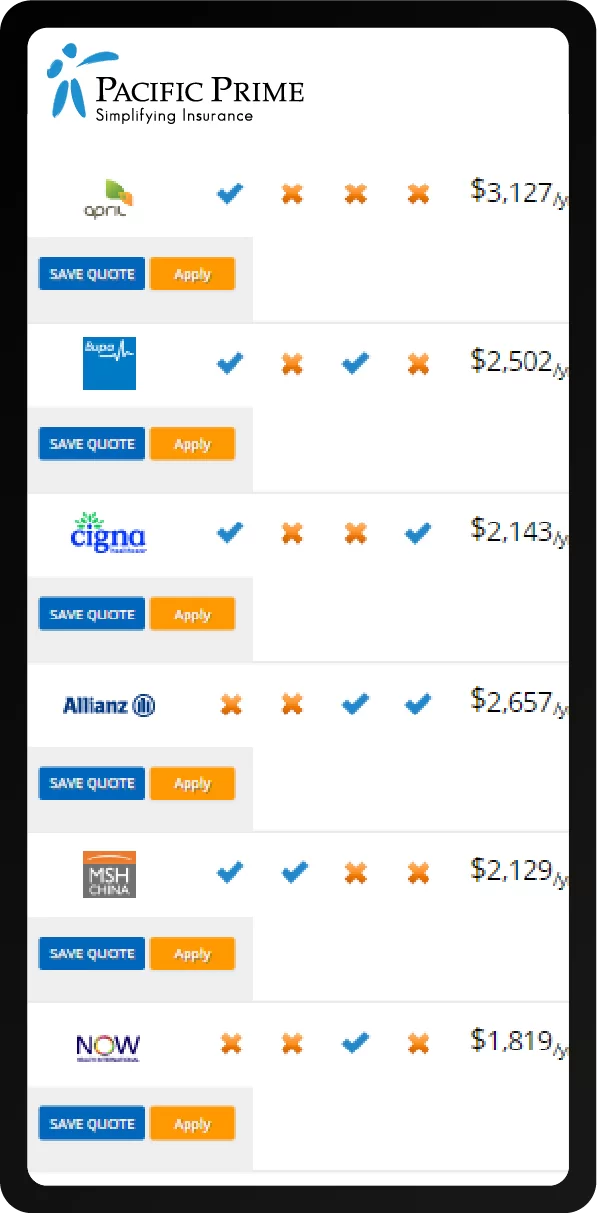
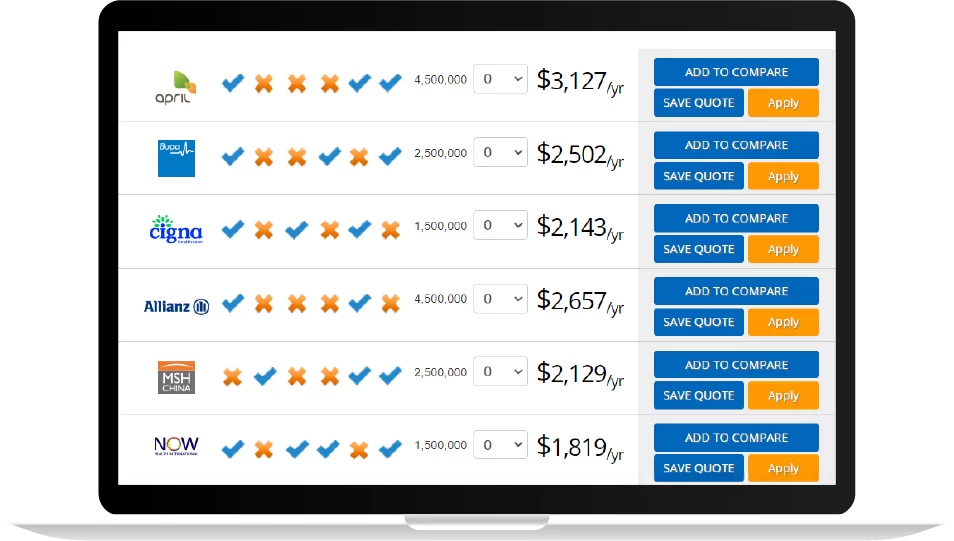
The best way to find the right international health insurance provider for the best coverage while working abroad is to compare quotes and plans from multiple companies. You will also want to make sure the provider has a network and experience in your destination country or region of the world.
If you have questions, contact an insurance expert for free online or by calling 1-800-868-1451.
Working Abroad? Have Pacific Prime Help You With Your Insurance Needs!
If researching international health insurance is overwhelming, there is free help available. At Pacific Prime, we work with multiple insurance companies to offer free quote comparisons and impartial advice to expats seeking the right international health insurance.
Pacific Prime has over 25 years of experience in the insurance industry, and this expertise enables us to select the best plans for you based on your unique needs and budget.
Contact us today for a FREE no-obligation plan comparison!
Frequently Asked Questions
How much will international health insurance cost?
International health insurance for an individual costs between USD $3,900 to $15,296 annually, depending on the global region of coverage and policy specifics. Insurance costs vary because the price of medical treatments varies around the world.
What happens if you need to go to the hospital while abroad?
If you need to go to the hospital while abroad, contact your international medical insurance company to be directed to a hospital on your plan. Without international medical insurance, you will be expected to pay for incurred medical costs.
What is the best international health insurance?
The best international health insurance comes from leading providers such as Cigna, Bupa Global, Allianz Care, AXA, and IMG. That said, the best plan is ultimately the one that aligns with your specific healthcare needs, coverage preferences, and budget.
With her background as an avid traveler and as an exchange student in Spain, Palida values the benefits of insurance and understands the frustrations that may come with making the best decisions for your health and safety in an unknown environment. Here at Pacific Prime, she aspires to create content that will help expats and travelers understand international health insurance with ease.
In her spare time, Palida enjoys reading short stories as much as binging on sitcoms. She is also a self-proclaimed "foodie" with the goal of trying as many cuisines from all over the world as possible. Combining her passion for writing with her love for food, she is an aspiring Google Local Guide reviewer.
- Pediatric Healthcare in Mexico for Expat Families (2026 Guide) - August 25, 2026
- LUMA Thailand Insurance Guide for Expats in 2026 - July 29, 2026
- GIG Gulf Insurance for Dubai Expats in 2026 - April 27, 2026
Comments
2 Comments
What are some unexpected costs that expats might face even with international health insurance coverage? How can I best prepare for these additional expenses while living abroad?
Even with international health insurance, expats might face unexpected costs such as deductibles, co-pays, exclusions for pre-existing conditions, or treatments that require out-of-pocket payment before reimbursement. Other costs could include non-covered services like dental care, alternative treatments, or elective procedures, as well as additional expenses for medical evacuation or repatriation in emergencies. To prepare, it’s important to thoroughly review your policy, budget for potential gaps, and maintain an emergency fund for unforeseen healthcare-related costs.
For expert advice on selecting or optimizing your international health insurance plan, reach out via our Contact Us page.
Leave a Comment